Insights
ANALYSIS: SpaceX did not go public hoping to become a trillion-dollar company. It went public already priced as one.
The unprecedented rise of the Magnificent 7 (“Mag 7”) became the defining public equity market story of the last four decades. Not since the Nifty-50 of the 1970’s has such a small set of companies dominated indices and equity market returns. However, most of the Mag 7 started life in public markets at valuations that now look tiny. SpaceX is different. It did not IPO at the “early public compounder” stage. Its valuation was rich upon arrival at IPO meaning vast amounts of wealth had already been crated for early private investors.
At IPO Amazon listed as an online bookstore, Apple as an early PC maker, Nvidia as a niche graphics-chip company, Tesla before its Model S cars had reached scale and Microsoft came to market as a profitable but still sub-$1bn revenue software company.
SpaceX arrived in the public market as an instant mega-cap company. At $135/share, the IPO valued it at roughly $1.77tn and after the day one pop, closed at $160.95 (up a 19.2%) it was worth around $2.1tn. Its starting valuation was already ~13x larger than the combined IPO-era valuations of Apple, Microsoft, Amazon, Alphabet, Meta, Nvidia, and Tesla.
That stretched valuation becomes even harder to defend when viewed against growth. SpaceX was already operating at scale, with $18.7 billion of 2025 revenue, but revenue grew ‘only’ 33% year over year. That is strong in isolation, but it is far less compelling than the growth profiles investors were underwriting in the previous Mag 7 IPOs.
At IPO, Amazon was growing revenue at over 2,100% on a trailing-twelve-month (TTM) basis, admittedly from a tiny base. Nvidia’s latest disclosed nine-month revenue was up 1,574%. Tesla’s most recent fiscal-year revenue was up 659%,; Google’s IPO-period TTM revenue was up 157% and Facebook’s TTM revenue was up 88%. In other words, SpaceX came public investors with far more revenue scale but materially less top-line momentum than its Mag 7 counterparts.
Facebook is probably the closest comparison to SpaceX because it was already a large, proven, highly monetisable platform at IPO. But even Facebook’s valuation looks small next to SpaceX. Facebook launched on public markets at about $104bn market cap, around 28x TTM and 221x trailing free cashflow (FCF), while growing revenue 88%. Facebook also had positive free cash flow of ~$470m, equal to a low-teens FCF margin.
SpaceX, by contrast, went public at roughly $1.77tn market cap, or about 95x 2025 revenue, while generating roughly -$14bn of negative free cash flow on $18.7bn of revenue. That is a -75% FCF margin. Put simply, Facebook was already producing cash; SpaceX was burning around $0.75 of cash for every $1 of revenue. After the first day rally of 20%, SpaceX was closer to 113x sales, and at points traded nearer 119x sales. Rather apt for a space company, that’s an out of this world valuation.
Facebook looked expensive at IPO at 28x sales, but with hindsight (and assuming todays price is fair) it was actually cheap. I ran a high-level “perfect foresight” DCF using Facebook’s actual free cash flow since IPO, then applied today’s P/FCF multiple as the terminal value and discounted it all back at an 11.5% WACC. That gives an implied equity value at IPO of around $433bn, or $157.90 per share. Facebooks actual IPO price: $38 per share. Put simply, investors could have paid 4.2x the actual IPO price and still made a 11.5% return since IPO.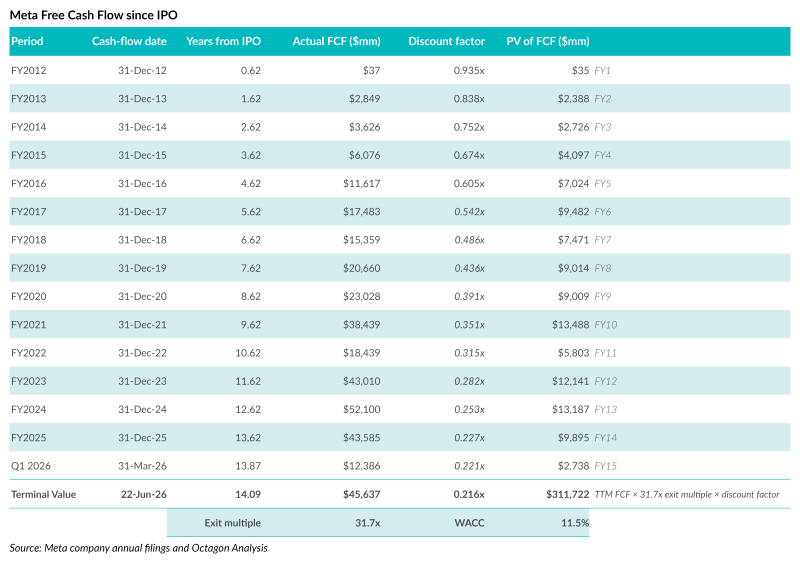
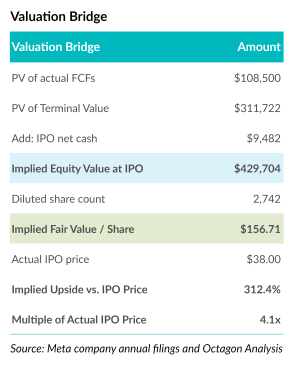
But that conclusion only works because Facebook delivered growth unlike the world had seen before. To underwrite that $157.90 implied IPO fair value in 2012, you would have needed to correctly forecast revenue growing from $3.7bn to roughly $201bn, a 54x increase in 14 years, or around 33% CAGR. You also would have needed to forecast free cash flow growing from about $470m in 2012 to more than $43bn today, while assuming the business could still command roughly a 32x FCF exit multiple years later. That is not normal underwriting, it is quite literally unprecedented growth for the time.
The readthrough to SpaceX is where it gets interesting. Facebook’s actual IPO multiple was 28x sales. Based on the perfect-foresight DCF, investors could have paid 4.2x more, which means the hindsight “fair” multiple was effectively around 118x sales (28x4.2). SpaceX IPO’d at around 95x sales and later traded close to 119x sales. So, on the surface, SpaceX is already trading near the kind of sales multiple that only made sense for Facebook after knowing it would become one of the best companies in history.
The problem is that SpaceX, due to its price, has a much higher performance hurdle to achieve excess returns above what the market demands. Facebook IPO’d with $3.7bn of revenue, 88% growth, and positive FCF. SpaceX is starting with $18.7bn of revenue, around 33% growth, and -$14bn of FCF. Bigger revenue bases are harder to compound at extreme rates, and SpaceX probably has a lower steady-state FCF margin than Meta because it is more capital intensive. Meta sells ads on software infrastructure; SpaceX builds rockets, satellites, terminals, launch infrastructure, and potentially entire space networks. The cash conversion profile is unlikely to look as clean as an asset-light advertising platform.
SpaceX is not being priced like Facebook at IPO. It is being priced closer to what Facebook was worth with perfect hindsight. The market is underwriting growth comparable to Meta since IPO and Investors are being asked to pay for this growth upfront. This is for a company starting from a much larger revenue base, growing slower than Facebook did at IPO, burning significant cash, and likely facing lower long-term cash conversion.
SpaceX does not need to be just a good company from IPO for it to achieve at market return; it needs to become one of the greatest compounding stories ever delivered on earth (and likely beyond). Miracles happen – but they are rare.
James Cameron is an Equity Analyst for Octagon Asset Management.
Disclaimer: This article has been prepared in good faith based on information obtained from sources believed to be reliable and accurate. This article does not contain financial advice. Some of the Octagon portfolios may own securities issued by companies mentioned in this article.
Octagon Asset Management is the investment manager for Octagon Investment Funds and the Summer KiwiSaver scheme.